For internationals living in Germany
The short way to a home of your own — plus independent advice on property investment, insurance and retirement. We are brokers, not a bank, so we compare hundreds of lenders instead of selling you one product.
Why independent matters
A bank advisor can only offer you what their own bank sells. We are independent, so your application goes to hundreds of banks and building societies at once — and you get to see the conditions and the reasoning behind them, not just a recommendation.
Illustration · how a comparison looks
Illustrative example with made-up rates, not current offers from any named institution. On a €400,000 loan, 0.5 % of interest is roughly €2,000 a year.
Built for internationals
A residence permit, a short SCHUFA history, income earned abroad, a partner who has not moved over yet — these are the details that decide whether a mortgage in Germany is approved, and most advisors rarely encounter them. With expat clients we work with them every week.
From first question to the keys
Fifteen minutes on where you stand. No documents to prepare, nothing to sign, no cost.
Hundreds of lenders instead of one — including a financing certificate you can show a seller.
We handle the paperwork and the bank’s questions, right through to the money being paid out.
We are still the people you call when your fixed rate ends or your situation changes.
Run your own numbers first
Nine free calculators for life in Germany — mortgage affordability, gross to net salary, the pension gap, health insurance and more. All built on the official 2026 figures. No sign-up, no email, and no sales call unless you ask for one.
How much property can I afford?
Your household income and savings against a realistic price — with the purchase costs of your German state already taken off.
Get started →What is actually left of my salary?
Gross to net with every line of a German payslip explained — tax class, church tax and all four social contributions.
Get started →Will my German pension be enough?
What the state will actually pay you, what is missing against the income you want, and what closing that gap would cost after tax relief.
Get started →Public or private health insurance?
What GKV and PKV would each cost you per month, whether you are employed or self-employed — and whether you may switch at all.
Get started →Rent or buy — where is the break-even?
Both paths compared on net worth, year by year, including the purchase costs that never come back to you.
Get started →Does a rental property pay off?
Monthly cash flow before and after tax, with the depreciation rate you choose, maintenance reserve and renovation relief.
Get started →My fixed rate is ending — what now?
What is left on the loan, what the follow-on offers cost, and whether the ten-year statutory termination right applies to you.
Get started →How much can I borrow as a freelancer?
Based on declared profit across several years, after tax and the health premium you carry on your own.
Get started →What does a company pension really cost me?
Converting gross salary costs less net than it looks. See the tax and contribution savings and the employer subsidy.
Get started →Guides
Written for expats and internationals who did not grow up with the German system. Each guide answers one question in full and has the matching calculator built into the page.
Who you would be talking to
Both of us have Indian roots and built our careers in Germany. We know what it is like to work out a foreign financial system from scratch — which is why we take the time to explain things properly instead of handing you a form.
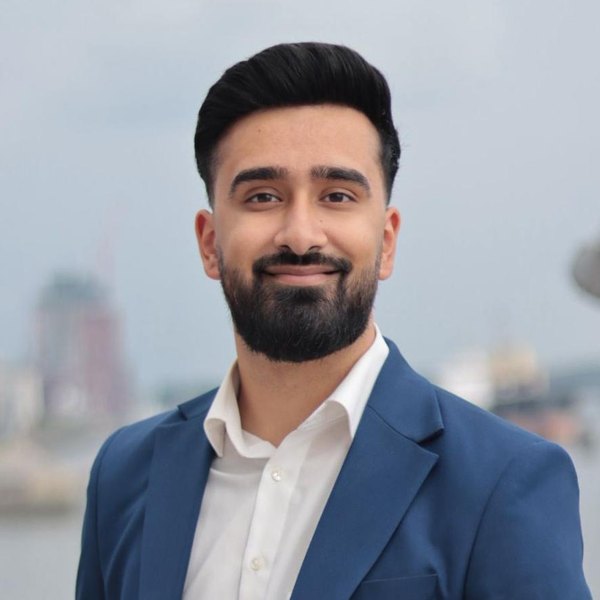 Kashish Arenja
Managing Director
More than eight years in German finance and over 400 clients guided into a home of their own. Indian roots, grew up in Germany. Speaks German, English and Hindi. Football, padel and travelling when he is not working.
"What matters to me is finding a solution that genuinely fits what someone wants."
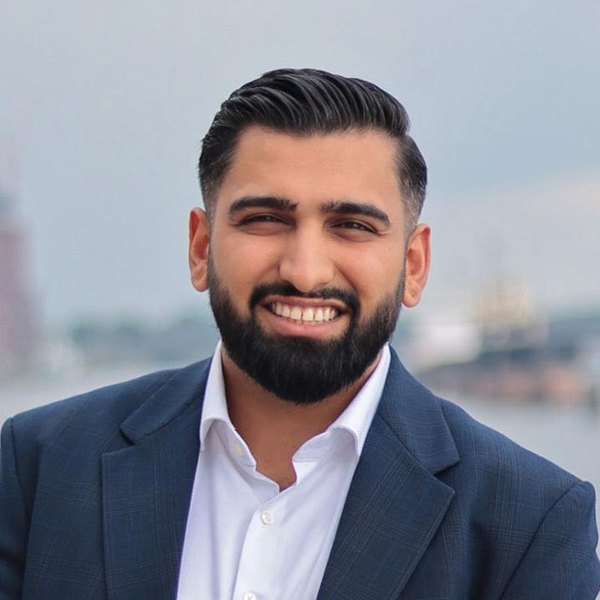 Mayur Raj
Managing Director
A trained bank clerk and mortgage specialist with many years in the industry. Indian roots, lives in Hamburg. Speaks German, English and Hindi. Football and travelling outside of work.
"I enjoy helping people turn the dream of their own home into something real."
Before you book a call
Nothing. On a mortgage, the lender pays us a commission once the loan is paid out, and the rate is the same whichever lender you choose — so we have no reason to push you towards one over another. The first call is free either way, and there is nothing to sign.
Yes. German lenders look at your income, your residence status and your credit record — not your nationality. With an EU Blue Card or permanent residence, most treat you like any other applicant. With a time-limited permit, fewer lenders will say yes, which is exactly where an independent broker earns their keep.
As a rule, you should cover the purchase costs from your own savings — roughly 8 to 15 % of the price, depending on the state and whether an estate agent is involved — because banks rarely finance them. Anything above that lowers your interest rate. Financing 100 % of the price is possible on a strong income, but it costs noticeably more.
Yes — German, English and Hindi, all in-house. Contracts and bank documents stay in German by law, so we go through the important passages with you and explain what each clause actually means.
They use the official 2026 figures and the real income tax tariff, so they are accurate enough to plan with. They are still illustrations rather than offers: what a particular bank will actually lend you depends on documents we would go through together.
Fifteen minutes on where you stand, what you want to do, and what is realistic. Nothing to prepare and nothing to sign. And if buying is not the right move for you right now, we will tell you so.
Most people come to us with one question and leave with two more answered. The first call is free and there is nothing to sign — at worst, you find out what your options are and go away to think about them.
Book a free call 15 minutes — pick a time that suits you Arenja & Raj Finanz